


News
Piramal Pharma Returns to Profit in Q2 FY27 as CDMO Revenue Jumps 36%, Raises FY27 Outlook
Piramal Pharma Returns to Profit in Q2 FY27 as CDMO Revenue Jumps 36%, Raises FY27 Outlook
![]() By eHealth Network - 28 October 2026


Piramal Pharma Limited has returned to the black in the September quarter, with its contract development and manufacturing (CDMO) business leading a broad-based recovery and prompting the company to raise its full-year growth outlook.
For Q2 FY27, the Mumbai-headquartered company reported consolidated revenue from operations of ₹2,617 crore, up 28% from ₹2,044 crore a year earlier. EBITDA rose 72% to ₹385 crore, lifting the EBITDA margin to 14.7% from 11%. Net profit came in at ₹5 crore, against a loss of ₹99 crore in Q2 FY26.
Advertisement
Investors welcomed the turnaround. Piramal Pharma shares gained about 12% in early trade on Wednesday, 28 October, even as the broader market and the pharma index were under pressure.
CDMO drives the quarter
The CDMO arm, Piramal Pharma Solutions, posted revenue of ₹1,424 crore in the quarter, a 36% year-on-year jump. Over the first half, the business grew 28% to ₹2,611 crore, with India and North America leading performance across the company’s manufacturing network.
The company said strong RFP activity and order inflows helped it add 22 new customers in H1 FY27. Its Phase III pipeline expanded to 28 molecules from 25 at the end of March 2026. Innovation-related revenues grew 24%, while on-patent commercial manufacturing revenues rose 39% in the half.
Antibody-drug conjugate (ADC) services remained a standout, with revenues up 51% year-on-year in H1. Piramal also strengthened its biologics capabilities by acquiring a controlling stake in Yapan Bio, and said the expansion at its Lexington, US site, which will add sterile fill-finish capacity to complete its integrated ADC offering, remains on track.
Quality record and other businesses
On compliance, the company said it completed 12 regulatory inspections and hosted 110 customer audits during H1 FY27, while keeping its record of no Official Action Indicated (OAI) classifications across US FDA inspections. That stands out at a time when regulatory scrutiny of Indian manufacturing sites is in sharp focus.
The Complex Hospital Generics (CHG) business grew 32% to ₹849 crore in the quarter, helped by inhalation anaesthesia sales in markets outside the US and the integration of Kenalog. Piramal said it retained a 48% value share of the US sevoflurane market and the top position in US intrathecal baclofen, citing IQVIA data.
Piramal Consumer Healthcare grew 13% to ₹359 crore, with its Power Brands up 21% and e-commerce up 32% in the half. The company noted that its distribution agreement with Bayer will expire in December 2026 and said the transition is not expected to materially affect FY27 guidance.
Outlook raised
On the back of the first-half performance, Piramal Pharma now expects FY27 revenue growth of 19% to 20%, with meaningfully higher profitability.
“We delivered a strong H1FY27, with revenue growth of 23% and EBITDA margin expansion of over 350 basis points, driven by healthy demand across our businesses, disciplined execution, and improved operating leverage,” said Nandini Piramal, Chairperson, Piramal Pharma Limited. “With H2 typically stronger than H1, we are well positioned to deliver a strong full-year performance, supported by a healthy order book, encouraging customer engagement, and continued operating discipline.”
For India’s pharma services sector, the results add to evidence that global sponsors are steadily widening their outsourcing to Indian CDMOs, especially in high-value areas such as ADCs, biologics and sterile injectables.
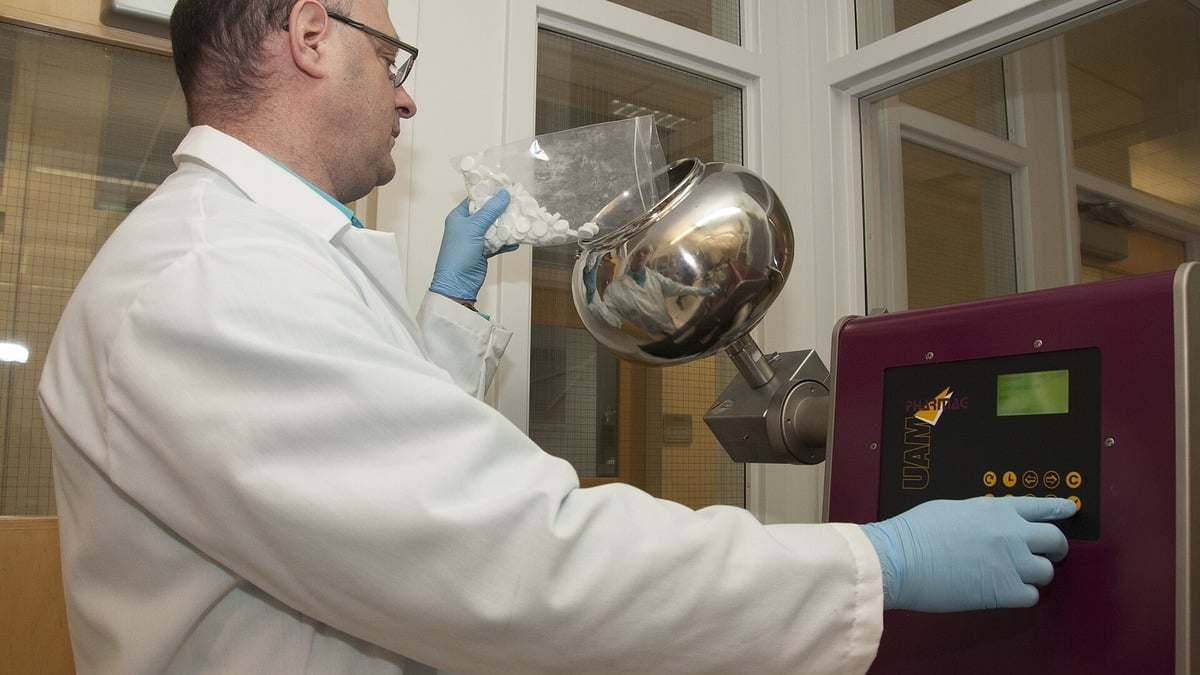
Image: U.S. Food and Drug Administration / Wikimedia Commons (public domain), representative image.

 Like
 Dislike
Be a part of Elets Collaborative Initiatives. Join Us for Upcoming Events and explore business opportunities. Like us on Facebook , connect with us on LinkedIn and follow us on Twitter , Instagram.
"Exciting news! Elets technomedia is now on WhatsApp Channels Subscribe today by clicking the link and stay updated with the latest insights!" Click here!